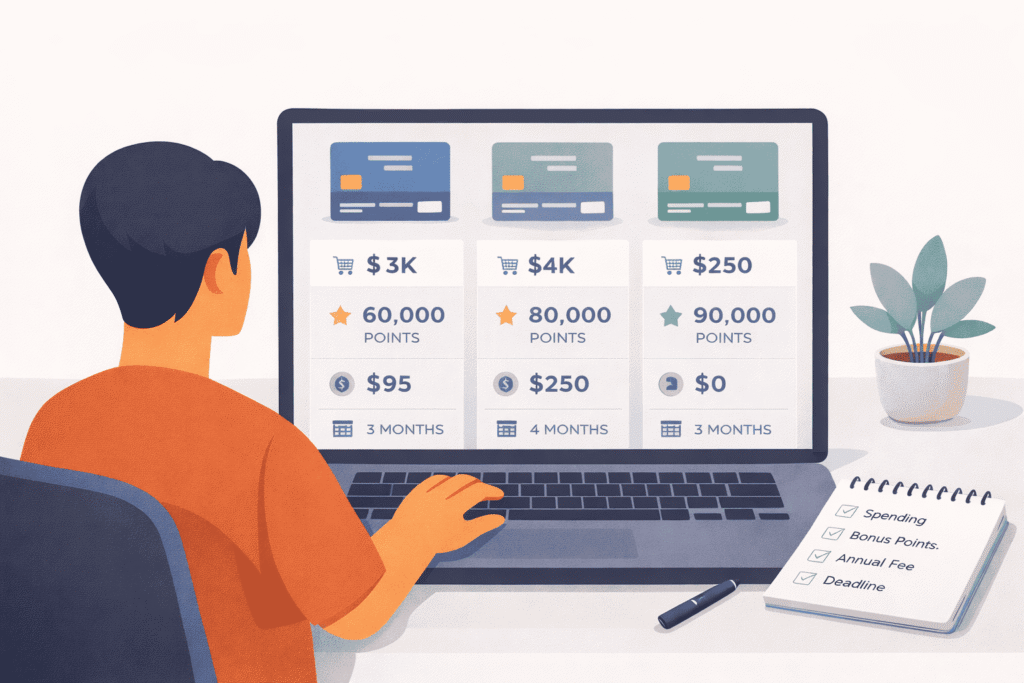
A welcome offer can add meaningful first-year value, but the headline number does not tell you whether the offer is a good fit. Credit card welcome bonuses depend on eligibility rules, spending requirements, deadlines, fees, and how useful the rewards are after they post.
This guide explains how to compare credit card welcome bonuses without letting a large points or miles number make the entire decision for you.
Quick Answer
- Best for: people comparing two or more card offers; beginners trying to understand large bonus numbers; travelers who want to compare offers using realistic value rather than marketing alone.
- Worth considering when: the spending requirement fits purchases you already planned, the rewards have a realistic use, and the card still has a clear role after the introductory offer.
- Skip or reconsider when: you would need unnecessary purchases to reach the threshold, interest or fees could overwhelm the reward value, or you do not understand how you would use the rewards.
- What you need: the offer amount, spending requirement, deadline, annual fee, eligible-purchase rules, reward currency, and a realistic redemption plan.
- Biggest gotcha: comparing bonus totals across different rewards programs as though every point or mile had the same value.
- Next step: write down the complete offer terms, estimate whether normal spending can meet the requirement, and evaluate the card after the bonus is gone.
What a welcome bonus actually is
A credit card welcome bonus is an introductory offer that may provide points, miles, cash back, or another reward after specified requirements are met.
The headline reward is only one part of the offer. The terms may also specify a spending threshold, time period, eligible purchases, account eligibility, annual fee, and other conditions.
That means two offers advertising similar point totals can have very different practical value.
Start with the spending requirement
The first question is not “How large is the bonus?” It is “Does the spending requirement fit expenses that were already going to happen?”
- Amount: how much eligible spending is required?
- Deadline: how long do you have to meet the requirement?
- Eligible purchases: which transactions count under the current offer terms?
- Normal spending: can the requirement be met with purchases you already expected to make?
- Payment cost: would pursuing the offer create interest, fees, or unnecessary purchases?
Do not treat additional spending as free simply because it earns rewards. If reaching the threshold changes what you would otherwise buy, the extra spending belongs in the economic comparison.
A useful way to make the requirement more concrete is to convert it into a monthly spending pace. For example, a $4,000 requirement over three months is roughly $1,333 per month in eligible purchases. Compare that number with spending already in your budget before treating the offer as realistic.
This is only a planning shortcut. The issuer’s exact deadline and rules control, and the offer period may not line up perfectly with calendar months. Record the actual start date and deadline from the offer terms instead of assuming you have a standard amount of time.
How to compare the value of different welcome bonuses
To compare the value of different welcome bonuses, separate the headline reward from the real cost of earning and keeping it. The goal is not to assign every point a universal value, but to compare each offer using the same assumptions.
A simple comparison framework is:
- Estimated reward value: what the bonus could realistically be worth for redemptions you are likely to make.
- Minus first-year annual fee: include the fee when it applies during the period in which you earn the bonus.
- Minus additional costs: include interest, fees, or unnecessary spending created specifically to reach the requirement.
- Then compare ongoing fit: consider whether the card still provides useful value after the introductory offer is gone.
Example with assumptions: suppose Offer A provides an estimated $600 of usable reward value after $3,000 of required spending and has a $95 first-year annual fee. Offer B provides an estimated $750 of usable reward value after $5,000 of required spending and has a $250 first-year annual fee.
The simplified net welcome value would be about $505 for Offer A and $500 for Offer B before considering normal rewards earned on the spending or other card benefits.
You can also normalize the comparison by dividing that simplified net welcome value by the required eligible spending. In this example, Offer A produces about 16.8 cents of net welcome value per required dollar, while Offer B produces about 10 cents. This is a comparison tool, not a guaranteed investment return or a universal measure of card value.
This does not mean Offer A is universally better. Redemption plans, benefits, fees, eligibility rules, spending capacity, and long-term card value can change the result. The important part is using the same assumptions for every offer.
Compare the financial terms too
A rewards offer still sits on top of a credit card account. APR, annual fees on travel cards, and other relevant charges should be considered alongside the bonus.
Consumer.gov’s credit card guidance recommends comparing multiple cards and looking at annual fees, APR, and other fees rather than evaluating one feature in isolation.
If borrowing costs or unnecessary fees exceed the realistic value of the rewards, a large advertised bonus does not automatically create a strong result.
When a welcome offer can make sense
Worth considering if…
- the spending requirement fits purchases you already planned
- you understand the reward currency and have a realistic use for it
- the card has a useful role after the introductory offer is gone
- the annual fee and other applicable costs make sense for your expected usage
Reconsider if…
- the spending threshold requires purchases you would not otherwise make
- you do not understand how the rewards can be redeemed
- the offer is attractive but the ongoing card has no clear purpose
- interest or other costs are likely to overwhelm the reward value
The useful balance is introductory value versus ongoing fit. A welcome offer can improve first-year value, but it should not turn an otherwise unsuitable card into a long-term strategy.
Step by step: How to compare credit card welcome bonuses
- Record the exact offer. Note the reward amount, spending requirement, deadline, annual fee, and important eligibility terms.
- Check normal spending. Estimate how much of the threshold can be met with purchases already in your budget.
- Understand the currency. Determine what the points, miles, or cash rewards can actually be used for.
- Use a realistic value. Base the comparison on redemptions you could reasonably make rather than an unusually valuable theoretical redemption.
- Include the annual fee. If the fee applies during the first year, treat it as part of the first-year comparison.
- Consider other relevant costs. Do not ignore interest or fees that could result from how the account is used.
- Evaluate the ongoing card. Look at normal earning, benefits, fees, and redemption options after the welcome offer disappears.
- Read the current issuer terms. The application page and disclosures should control the final understanding of eligibility and offer requirements.
Do not compare point totals as if they were identical
A 60,000-point offer in one program is not automatically better or worse than a 50,000-point offer in another.
Rewards currencies can differ in redemption options, transfer partners, award availability, restrictions, expiration rules, and the value available through different redemption methods.
If you are still learning how these currencies work, review Miles & Points 101 before comparing offers based mainly on the number of points advertised.
Rewards terms can change
Do not assume the practical value of a reward currency or benefit will remain fixed indefinitely.
The Consumer Financial Protection Bureau has identified potential consumer problems involving credit card rewards programs, including devaluation of rewards already earned, vague or buried conditions that prevent consumers from receiving rewards, and failures where rewards are deducted without the corresponding benefit being delivered. Read the CFPB credit card rewards circular.
That makes current offer terms and program rules more useful than assuming an advertised point balance has a permanent fixed value.
Example with assumptions
Example: This simplified scenario illustrates how to compare offers. It does not represent current offers from particular issuers.
- Offer A: smaller welcome bonus with a lower spending requirement
- Offer B: larger welcome bonus with a substantially higher spending requirement
- Traveler: has normal expenses sufficient to meet Offer A without changing spending habits
- Issue: reaching Offer B would require purchases the traveler had not otherwise planned
Option A: The smaller offer may produce less headline value, but its threshold fits spending that was already expected.
Option B: The larger offer advertises more rewards, but creating unnecessary spending to reach the threshold would reduce or potentially erase part of that advantage.
Conclusion: In this scenario, Offer A can be the more practical choice because the comparison includes the spending behavior required to earn the rewards—not just the advertised bonus total.
Look beyond year one
A welcome offer is temporary. The account may remain open for years.
After evaluating the introductory offer, ask what role the card would have without it:
- Does the normal earning structure fit your spending?
- Would you realistically use the ongoing benefits?
- Does the annual fee still make sense?
- Do the rewards still fit how you want to redeem?
- Would the account still have a clear job after the bonus is gone?
Our First Travel Rewards Card guide provides a broader framework for evaluating the ongoing account rather than only the introductory offer.
Common mistakes and gotchas
- Comparing points across different programs as if they had identical value.
- Creating unnecessary spending just to meet the threshold.
- Ignoring the annual fee when calculating first-year value.
- Ignoring APR or other borrowing costs while focusing on rewards.
- Choosing an offer without understanding the rewards currency.
- Missing the spending deadline or misunderstanding which purchases qualify.
- Assuming the largest headline bonus is automatically the strongest offer.
- Evaluating only the first year and ignoring the ongoing card.
- Assuming program rules and redemption values will remain unchanged.
Related reading
- Travel Credit Cards 101 — understand the different types of rewards cards before comparing introductory offers.
- How to Choose Your First Travel Rewards Card — evaluate the long-term card after separating it from the welcome offer.
- Miles & Points 101 — understand why point and mile totals from different programs cannot be compared as identical currencies.
FAQ
Should I always choose the largest credit card welcome bonus?
No. Compare the spending requirement, deadline, fees, rewards currency, realistic redemption value, and ongoing card rather than choosing by the headline number alone.
How do I know if a spending requirement is realistic?
Compare it with purchases you already expect to make during the offer period. If meeting the requirement depends on creating extra spending, include that behavior in the comparison rather than treating the rewards as free value.
How long do I have to meet a welcome bonus spending requirement?
There is no single deadline that applies to every welcome offer. The issuer’s current terms specify the spending window and when it begins. Record the exact deadline when you apply rather than assuming every offer gives the same number of months.
Does the annual fee matter when comparing bonuses?
Yes. If an annual fee applies during the first year, include it when evaluating the offer rather than comparing only the reward total.
What if two welcome offers look similar?
Compare the currencies, redemption options, spending requirements, ongoing earning, recurring fees, benefits, and how well each card fits the role you need.
Does a welcome bonus have the same value for cash and travel redemptions?
Not necessarily. The same points balance can produce different practical value depending on whether you redeem for cash, travel, transfers, statement credits, or another option. Use the redemption method you are realistically likely to choose when comparing offers.
Can a welcome bonus change after I apply?
Offer availability and public promotions can change. Save the applicable offer details and review the issuer’s current terms so you understand the conditions associated with your application.
Conclusion
Credit card welcome bonuses are most useful when you evaluate the entire offer rather than the headline reward total. Spending requirements, deadlines, fees, rewards usability, and the ongoing card all matter.
- Use spending you already planned rather than creating purchases for a bonus.
- Compare reward currencies by realistic use, not point totals alone.
- Include annual fees and other relevant costs in the comparison.
- Evaluate whether the card still has a purpose after the introductory offer.
- Review the current issuer offer terms before making a credit decision.
Last updated: October 3, 2026. Welcome offers, spending requirements, eligible purchases, APRs, fees, rewards, eligibility rules, and issuer terms can change. Review the current offer and issuer disclosures before making a credit decision.